Crypto Options Statistics for 2026
Explore crypto options statistics for 2026, from record ETF and CME activity to Deribit volumes, volatility resets and the rise of onchain options trading.

- Options are now the largest Bitcoin derivatives segment by open interest, with $65 billion compared with $60 billion in futures as hedging replaces leverage.
- Regulated rails rival crypto-native exchanges for the first time. BlackRock's IBIT captured a record 52% of Bitcoin options open interest, while CME activity is running 46% above last year.
- The next frontier is onchain. Decentralized options volume reached record highs from a tiny base. Hyperliquid's HIP-4 standard is positioned as the category's biggest potential catalyst.
Crypto options spent most of the market's history in the shadow of perpetual futures. By 2026, that relationship has changed. Bitcoin options open interest now exceeds futures, ETF options have reshaped the venue rankings, and hedging has overtaken raw leverage as the dominant positioning tool through a prolonged market consolidation.
Top 8 Crypto Options Statistics (2026)
These eight statistics cover the shift from futures to options, competition between regulated and crypto-native venues, and changing volatility conditions. They also examine Ethereum's distinct market structure and the early growth of onchain options trading.
1. Bitcoin Options Open Interest Overtook Futures at $65 Billion
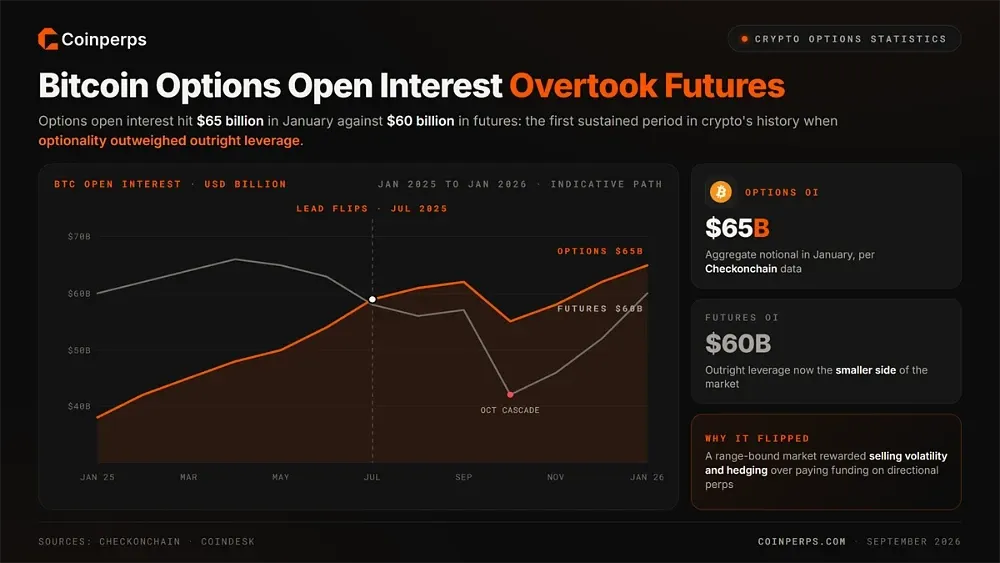
Aggregate Bitcoin options open interest reached $65 billion in January, compared with $60 billion of notional in futures, according to Checkonchain data reported by CoinDesk. Options have maintained their lead since July 2025, marking the first sustained period in crypto's history when optionality outweighed outright leverage.
A market that stopped trending drove the change. Following its late-2025 high, Bitcoin spent months trading within a broad range. Those conditions rewarded selling volatility, collecting premium, and hedging existing holdings more than paying funding on directional perpetual positions.
The effect is also visible in price behaviour. Dealer hedging around large strikes dampens volatility, although forced flows continue to move through futures. Reading both markets together through our open interest dashboard and liquidation data provides the fullest picture of positioning.
2. BlackRock's IBIT Reached 52% of Bitcoin Options Open Interest
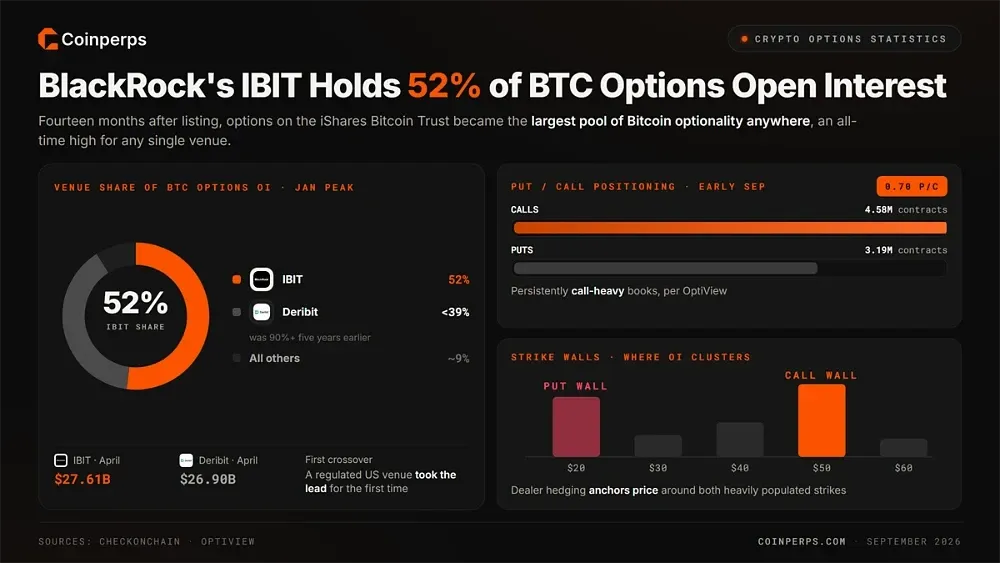
Within fourteen months of listing, options on BlackRock's iShares Bitcoin Trust transformed the venue landscape. Initially a complement to offshore platforms, IBIT has grown into the single largest pool of Bitcoin optionality anywhere.
Several measures illustrate the scale of the regulated takeover:
- Peak share: IBIT accounted for 52% of total Bitcoin options open interest in January, an all-time high for any single venue since aggregated cross-market records began.
- April crossover: IBIT open interest reached $27.61 billion that month, surpassing Deribit's $26.9 billion. A regulated United States venue took the lead for the first time.
- Deribit erosion: The crypto-native leader's share of Bitcoin options open interest fell below 39% in early 2026, compared with more than 90% only five years earlier.
- September positioning: In early September, OptiView recorded 4.58 million IBIT call contracts against 3.19 million puts. The resulting 0.70 ratio reflected persistently call-heavy positioning.
- Strike walls: Calls are most concentrated at the $50 strike, while puts cluster at $20. Dealer hedging flows anchor price behaviour around both heavily populated levels.
- Access effect: Brokerage accounts and retirement platforms can now trade Bitcoin optionality directly, as can equity market makers. This extends participation well beyond crypto-native exchanges and their existing clients.
Flows into the underlying fund remain the foundation of the IBIT options market. Current creations and redemptions are available on our Bitcoin ETF tracker.
3. Deribit Cleared $79.5 Billion of BTC Options in a Single Month
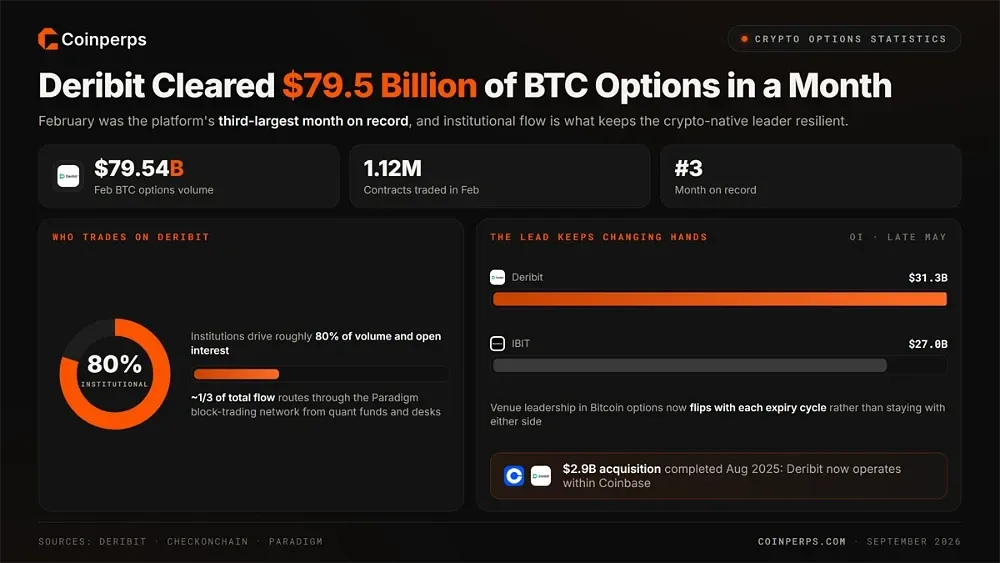
Deribit processed $79.54 billion in Bitcoin options volume across 1.12 million contracts during February, its third-largest month on record. Following the $2.9 billion acquisition completed in August 2025, the platform now operates within Coinbase, joining the parent of Coinbase Futures.
Institutional participation underpins Deribit's resilience. These clients account for roughly 80% of its volume and open interest. The Paradigm block-trading network alone routes around a third of total flow from quantitative funds and trading desks.
Deribit has not permanently surrendered venue leadership. By late May, its open interest had recovered to $31.3 billion, putting it back above IBIT's $27 billion. The lead in Bitcoin options now changes hands with each expiry cycle rather than remaining with either venue.
4. CME Crypto Options Activity Is Running 46% Above Last Year
Demand for regulated futures and options continues to grow at CME Group, where crypto products recorded unprecedented activity into 2026. Growth extends beyond everyday trading to periods of market stress, while the exchange's product range has expanded beyond Bitcoin and Ether.
CME's own disclosures document the trend:
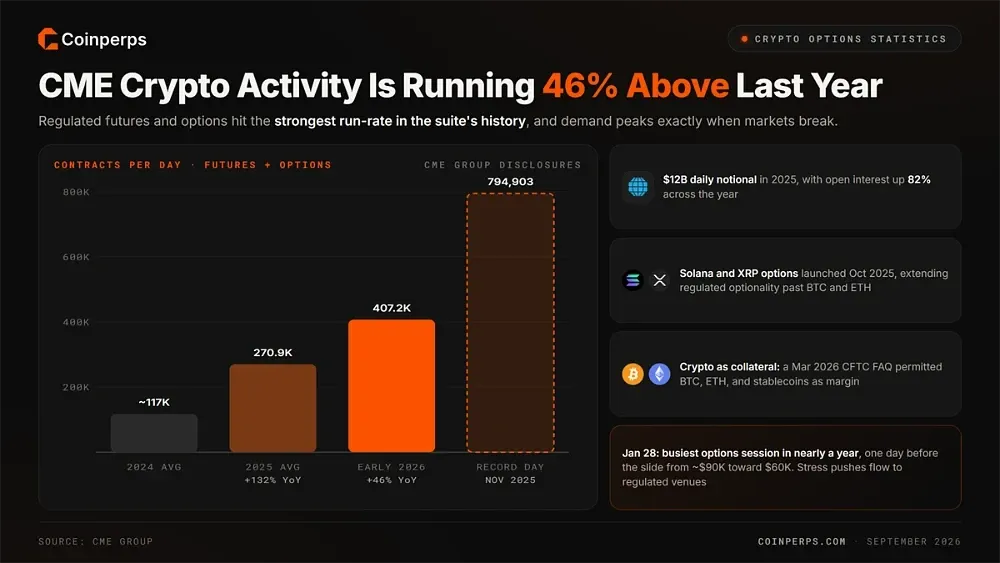
- Daily average: CME's crypto futures and options traded 407,200 contracts per day in early 2026, a 46% year-over-year increase and the strongest run-rate in the suite's history.
- Record session: A single day in November 2025 saw 794,903 contracts traded as volatility spiked. That surpassed the previous record, set only three months earlier under calmer market conditions.
- Full-year growth: Average daily volume climbed 132% during 2025 to 270,900 contracts, representing roughly $12 billion in notional. Open interest expanded 82% over the same period.
- Stress demand: January 28 was the busiest crypto options session in nearly a year. It came one day before the sell-off that took Bitcoin from about $90,000 toward $60,000.
- Altcoin expansion: Solana and XRP options launched in October 2025, extending regulated optionality beyond Bitcoin and Ether as institutional altcoin futures demand reached record levels.
- Collateral rules: A CFTC FAQ issued in March 2026 permitted Bitcoin, Ether, and payment stablecoins as margin collateral, reducing the operational cost of maintaining regulated derivatives positions.
The January crash revealed an important pattern. As markets were breaking, activity migrated toward regulated liquidity, reflecting the preference institutions show for venues they trust during periods of stress.
5. Bullish Built $3 Billion in Options Open Interest Within Months
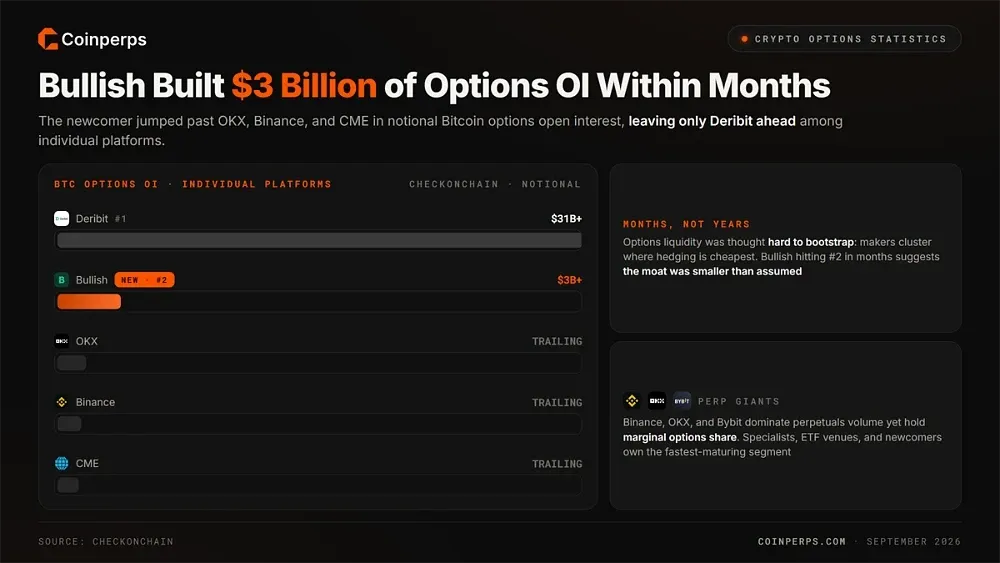
According to Checkonchain data, Bullish Exchange surpassed $3 billion in notional Bitcoin options open interest after only a few months of trading. That placed it ahead of OKX, Binance, and CME, leaving only Deribit ahead among individual platforms.
Options liquidity had long been considered difficult to bootstrap. Market makers tend to concentrate where hedging is cheapest, reinforcing the position of established venues. Bullish reaching second place within months suggests that this competitive barrier was smaller than previously assumed.
The rapid expansion also exposes a distinction between options and perpetuals trading. Binance, OKX, and Bybit dominate perpetuals volume but retain marginal options market share. Specialists, ETF venues, and newcomers have instead captured the fastest-maturing segment of the market.
6. Implied Volatility Collapsed From 95% to Around 40%
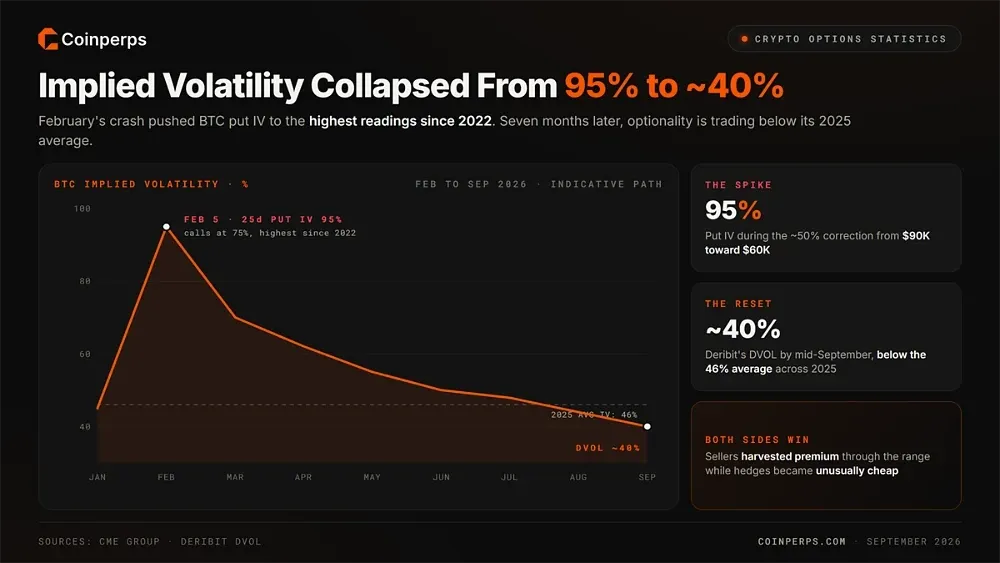
Bitcoin's 25-delta put implied volatility reached 95% on February 5, while calls climbed to 75%. According to CME Group research, these were the highest readings since 2022. The spike accompanied a roughly 50% price correction from about $90,000 toward $60,000.
Volatility subsequently underwent a sharp repricing. By mid-September, Deribit's DVOL index was near 40%, below the 46% average implied volatility recorded across 2025. Event premium faded as the market settled into its range between macro catalysts.
Lower volatility affects both sides of the options market. Premium sellers harvested income during the consolidation, while hedgers and directional buyers found protection unusually inexpensive. Traders can monitor that spread through The Block's implied volatility dashboards alongside our BTC perpetuals data.
7. Ethereum Options Remain a 90% Single-Venue Market
Ethereum's options market expanded substantially through the cycle without experiencing the same diversification across venues as Bitcoin. The migration toward regulated platforms that transformed BTC optionality has had little effect on ETH so far.
The figures reveal a highly concentrated market:
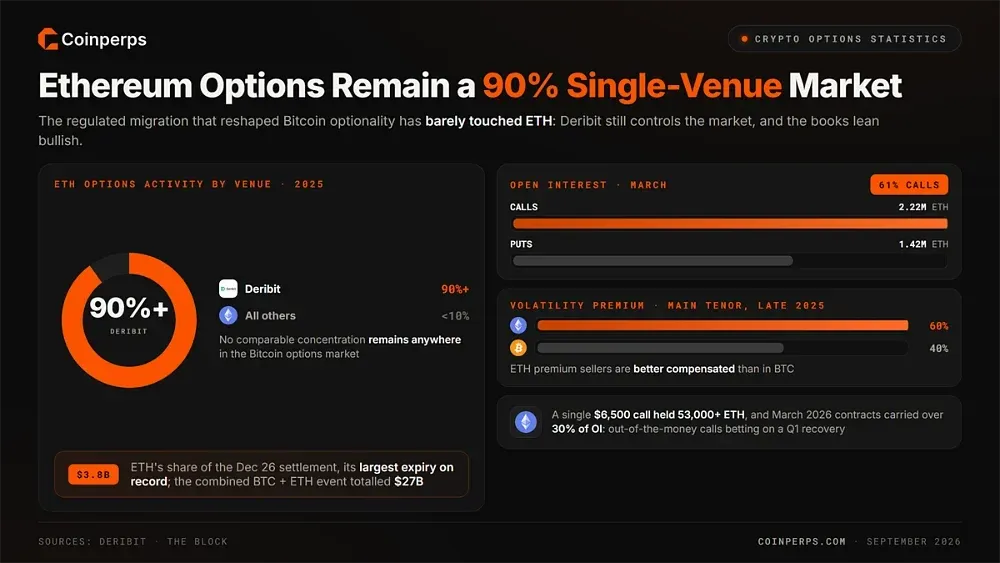
- CEXs share: Deribit controlled more than 90% of Ethereum options activity through 2025. No comparable degree of concentration remains anywhere in the Bitcoin options market.
- Record expiry: Ether accounted for $3.8 billion of the December 26 settlement, its largest single options expiry on record. The combined Bitcoin and Ether event totalled $27 billion.
- Call tilt: Calls made up 61% of Ethereum options open interest in March, covering more than 2.22 million ETH. Put positions accounted for roughly 1.42 million ETH.
- Whale strikes: A single $6,500 call position on Deribit held over 53,000 ETH. Further bullish clusters appeared between roughly $2,200 and $6,500 across later expiries.
- Volatility premium: Ether's main-tenor implied volatility remained near 60% late in 2025, compared with around 40% for Bitcoin. ETH premium-selling strategies were therefore comparatively better compensated.
- Quarterly anchor: March 2026 contracts represented over 30% of open interest following the December settlement. Out-of-the-money calls positioned for a first-quarter price recovery dominated those holdings.
Spot demand through funds remains the swing factor for this call-heavy positioning. Fund flows can be tracked on our Ethereum ETF tracker, with additional positioning data available on the ETH perpetuals page.
8. Onchain Options Hit Record Volume From a Tiny Base
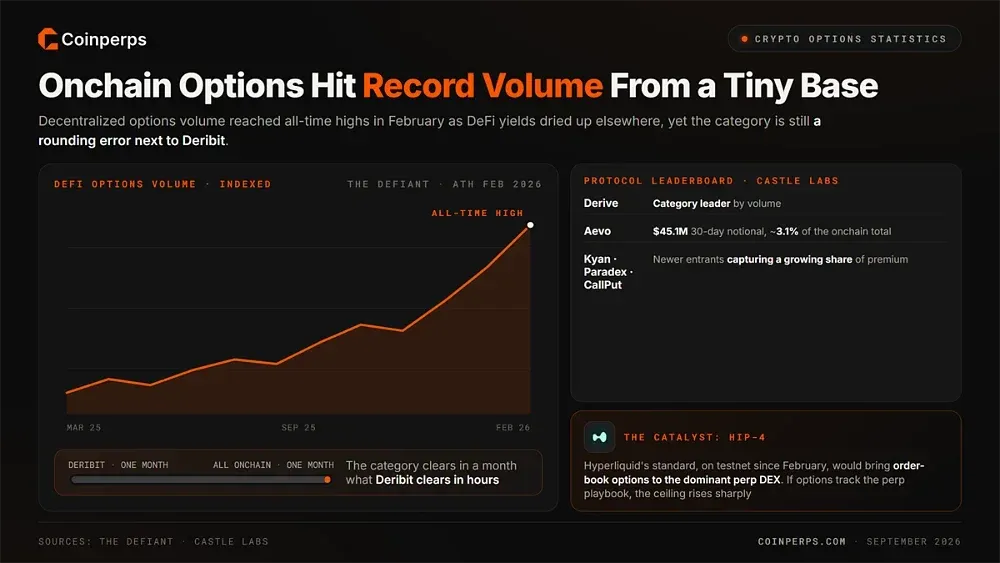
Decentralized options volume reached all-time highs in February, according to The Defiant, partly as DeFi yields dried up elsewhere. Absolute volumes remain small. The entire category processes in a month what Deribit can clear in hours.
Activity is nevertheless spreading across more protocols. Castle Labs research identifies Derive as the category leader, while Aevo generated $45.1 million in 30-day notional, representing about 3.1% of the onchain total. Newer entrants, including Kyan, Paradex, and CallPut, are capturing a growing share of premium.
Hyperliquid represents the potential catalyst. Its HIP-4 standard has been on testnet since February and would introduce order-book options to the dominant perp DEX. If options follow the trajectory of perpetuals, covered in our decentralized perpetual futures statistics, the category's ceiling could rise sharply.
How Crypto Options Statistics Are Measured
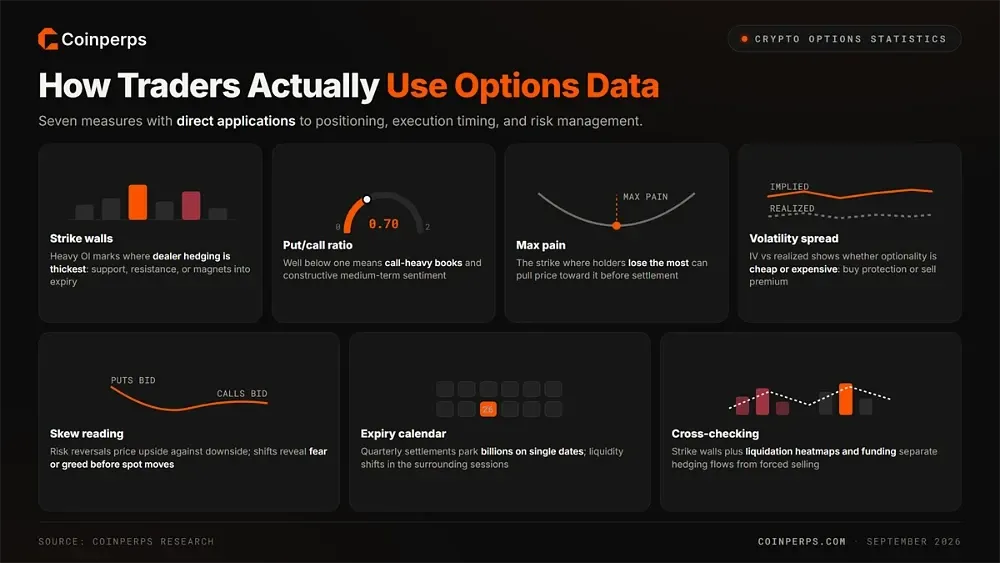
Options data can be harder to interpret than futures data because the same position may be measured in three different ways. Notional value represents the full underlying exposure. Premium measures the amount paid by the buyer, whereas contract counts do not account for dollar value. Trackers use different conventions, making it essential to check the units before comparing headline figures.
Open interest and volume also respond differently to expiries. Large quarterly settlements mechanically remove outstanding positions. Deribit's open interest, for example, fell from roughly $43 billion to $26 billion across the year-end expiry without an equivalent change in underlying demand or market health.
Comparisons between venues introduce another complication. ETF options are quoted in contracts on fund shares and reported through equity-market data feeds. Crypto-native venues instead use coin-denominated terms. Aggregators convert these figures into dollar notional, providing the common basis required for the venue rankings above.
Settlement style affects how the figures should be read. Deribit offers European-style, cash-settled contracts, while ETF options are American-style and can be exercised early. Consequently, identical open interest figures may involve different hedging pressures or expiry dynamics. Assignment risk also varies according to the venue holding the positions.
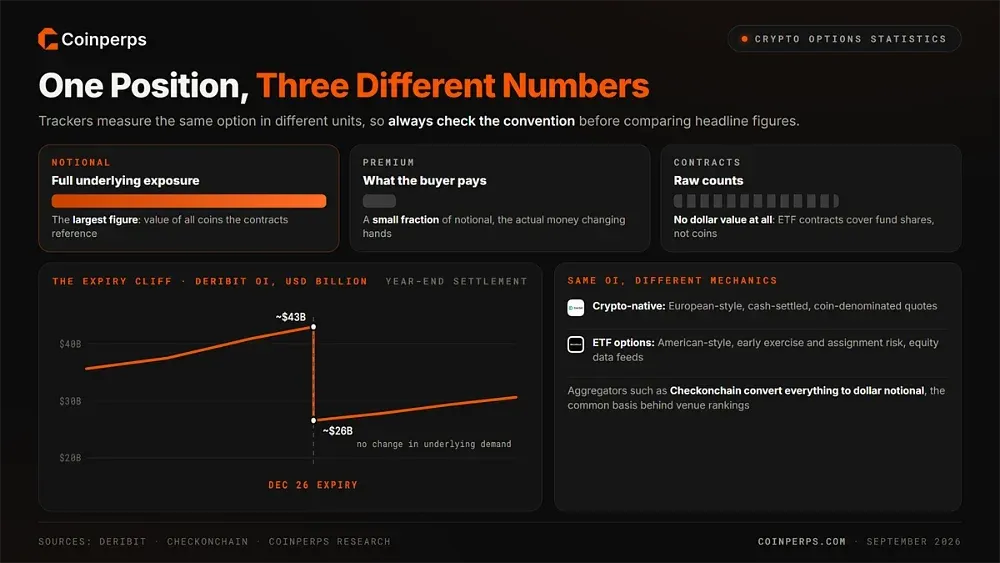
Regulated vs Crypto-Native Options Compared
Regulated and crypto-native venues now operate as two distinct ecosystems, pricing the same underlying assets through different trading infrastructure. The comparison below uses the measures examined throughout this page and draws on the sources cited above.
Neither ecosystem has secured a permanent lead. Regulated venues benefit from access to capital pools that will never open crypto exchange accounts, having captured almost all of the Bitcoin market's growth. Crypto-native platforms retain advantages in continuous trading and altcoin coverage, alongside their control of the Ethereum options market.
Weekend trading is the practical dividing line. A position hedged through Friday's close on a regulated venue remains unhedged until Monday. Crypto-native options and perpetuals therefore remain structurally necessary for traders managing risk throughout all seven days.
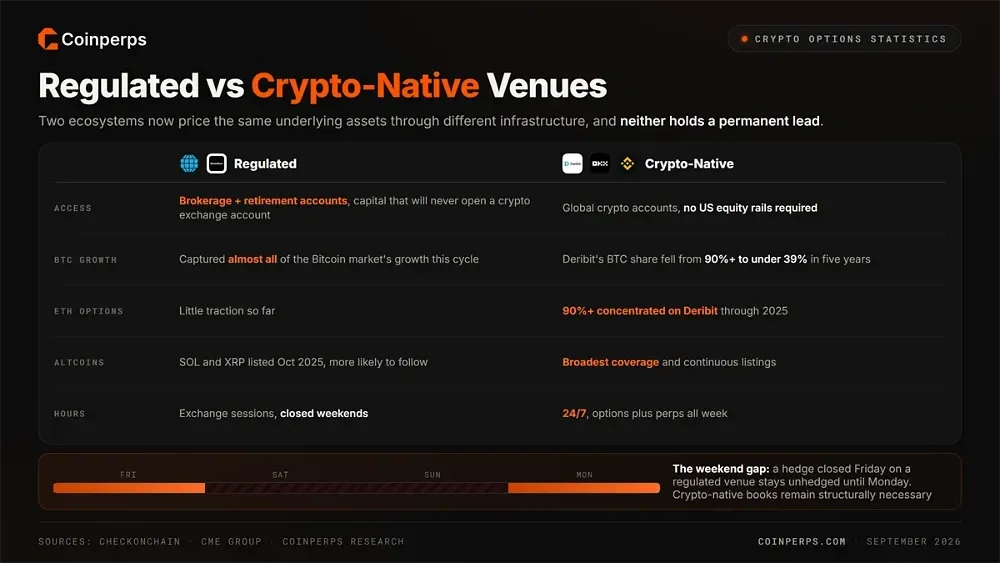
Why Hedging Overtook Leverage
The shift toward options followed a severe period of deleveraging. October 2025's $19 billion liquidation cascade was followed by a drawdown of roughly 50% into February. A generation of leveraged perpetual positions was wiped out, pushing futures open interest to multi-quarter lows as traders reduced leverage rather than exiting the market.
Defined-risk positions became more attractive in the market that followed. Maintaining directional exposure through perpetuals can slowly erode returns through funding payments when prices remain range-bound. A purchased option, by contrast, limits potential losses and cannot be liquidated. Our funding rates dashboard allows traders to compare the costs of both approaches.
ETF ownership subsequently turned a cyclical change into a structural one. Institutions holding spot exposure through funds use listed options to hedge as a matter of mandate. Their open interest grows with assets under management rather than speculative appetite. Our perpetuals versus futures guide explains where each instrument fits.
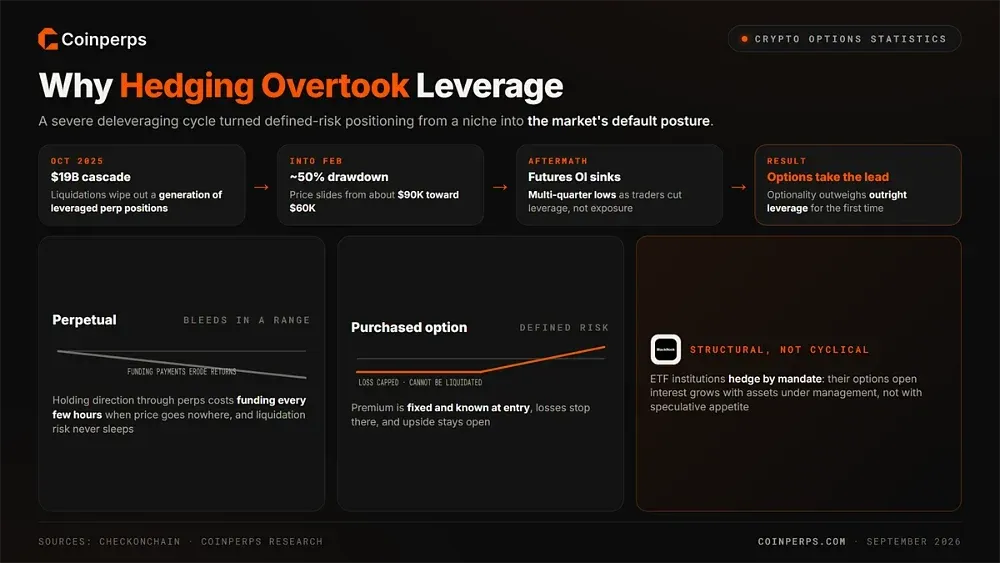
How Traders Use Options Data
Options statistics are most useful when they inform trading decisions. The following measures have direct applications to positioning, execution timing, and risk management:
- Strike walls: Concentrated open interest at particular strikes identifies where dealer hedging is heaviest. These prices often act as support, resistance, or magnets as expiry approaches.
- Put/call ratio: The relationship between outstanding puts and calls provides a reading of market positioning. Ratios well below one indicate call-heavy books and broadly constructive medium-term sentiment among traders.
- Max pain: The strike at which options holders collectively lose the most can draw prices toward it ahead of settlement. Our max pain guide examines this dynamic in detail.
- Volatility spread: Comparing implied volatility with realized volatility helps determine whether optionality is cheap or expensive. This informs the choice between buying protection and selling premium during established trading ranges.
- Skew reading: Risk reversals compare the price traders pay for upside exposure with the cost of downside protection. Changes in that relationship can reveal shifts in fear or greed before they become visible in spot prices.
- Expiry calendar: Quarterly settlements concentrate billions in notional exposure on individual dates. Volatility and liquidity conditions frequently change in the surrounding sessions, as do funding conditions.
- Cross-checking: Comparing strike walls with liquidation heatmaps and funding data helps distinguish hedging-driven price movements from forced deleveraging, improving the odds of trading the correct underlying catalyst.
Emerging Themes in Crypto Options
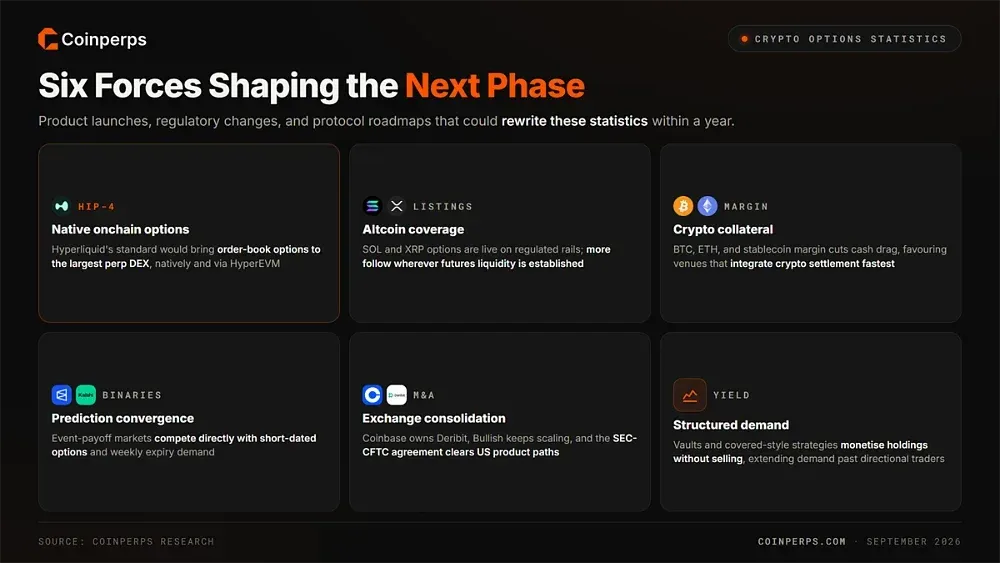
Product launches, regulatory changes, and protocol roadmaps are already shaping the next phase of the options market. Several developments could materially change the statistics covered here over the coming year:
- Native onchain options: Hyperliquid's HIP-4 standard has been on testnet since February. It would introduce order-book options to the largest perp DEX, both natively and through HyperEVM.
- Altcoin coverage: Regulated venues now list Solana and XRP options. Further listings appear likely wherever underlying futures liquidity becomes established on major institutional platforms.
- Crypto collateral: Margin rules permitting Bitcoin, Ether, and stablecoins as collateral reduce the cash drag on hedged positions. This favours venues that integrate crypto-native settlement most quickly.
- Prediction convergence: Binary outcome markets on prediction platforms increasingly compete with short-dated options. Their event-style payoffs overlap directly with demand for weekly expiry trading.
- Exchange consolidation: Coinbase owns Deribit, while Bullish continues to scale rapidly. The SEC-CFTC jurisdiction agreement also clears a path for additional United States products on compliant rails.
- Structured demand: Yield vaults and covered-style strategies allow holders to monetise existing positions without selling. Structured products built on options infrastructure serve the same purpose, extending demand beyond purely directional traders.
Bottom Line
Crypto options have matured during this cycle. Open interest has surpassed futures, a regulated venue briefly took the lead in Bitcoin optionality, and CME recorded unprecedented activity. Together, these developments point to a market increasingly built around risk management rather than pure speculation, even as headline crypto volumes remain below their peak.
Three developments will determine how the market evolves from here. The first is whether IBIT or Deribit maintains the open interest lead through the next quarterly cycles. The second is whether Ethereum options attract meaningful competition from regulated venues. The third is whether HIP-4 delivers the breakout moment for onchain options that perpetual DEXs have already experienced.
Methodology
This page combines data from cross-venue aggregators and exchange disclosures with equity-market options data and onchain research. Figures are converted to dollar notional wherever possible to maintain consistency across comparisons.
- Checkonchain via CoinDesk: Used for aggregate options-versus-futures open interest, venue share, and the IBIT and Bullish milestones.
- CME Group: Used for regulated contract volumes, open interest growth, record sessions, and implied volatility episodes.
- The Block: Used for implied volatility dashboards and options expiry breakdowns across Deribit and CME.
- OptiView: Used for IBIT contract counts, put/call ratios, and strike-level positioning data.
- Castle Labs and The Defiant: Used for onchain options protocol rankings, notional share, and category records.
- CEXs and industry disclosures: Used for Deribit monthly volume, acquisition details, expiry settlements, and regulatory dates.
FAQs
